Sabiha Zainulbhai
Deputy Director, Future of Land and Housing Program
Fahe builds the capacity of local financial ecosystems in rural communities to deliver homeownership financing at scale.
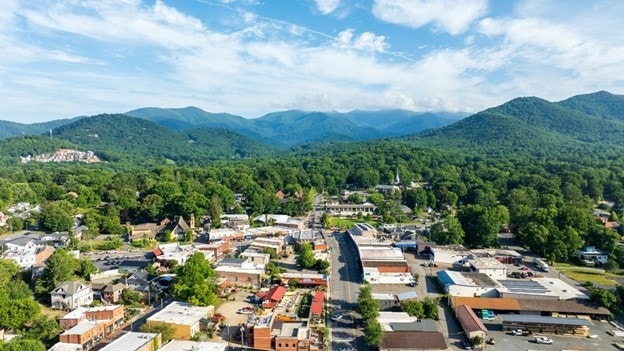
Fahe is a nonprofit network based in Kentucky dedicated to increasing access to capital in communities that lack traditional financing options, especially across Appalachia and in rural communities. The organization’s hub-and-spoke model allows Fahe (the hub) to provide tailored support to its over 50 nonprofit members (the spokes) by filling in capacity gaps—whether for a three-person nonprofit with deep community ties but no capacity to process loan applications, or for a 300-person Community Development Financial Institution (CDFI) that originates loans but needs an entity to buy those loans so they can generate capital without taking on additional debt. Collectively, these organizations are able to address the range of challenges that lower-income buyers face in accessing homeownership and ultimately increase access to mortgage financing for communities of color in underserved and rural areas.
The hub-and-spoke model has been particularly effective in the operation of the USDA 502 Direct Loan Program, which helps low- and moderate-income buyers in eligible rural areas access mortgage financing and home repairs. Similar to other government-sponsored loan products, these USDA loans typically do not require a downpayment, have low fixed interest rates, and are either funded directly by USDA (the Section 502 Direct Loan Program) or privately funded but backed by USDA (the Section 502 Guaranteed Loan Program). As the largest intermediary for USDA, serving over 10 states, Fahe is a liaison between low-income applicants and USDA, ensuring that all program criteria are met and loan applications are complete upon submission. Fahe’s intermediary role not only eases the process for the applicant but also bolsters the capacity of USDA to deliver financing, which has been critical given the program’s persistent staffing shortages.
Fahe's hub-and-spoke model, commitment to boots-on-the-ground community engagement, and adaptive program delivery demonstrate a replicable framework for increasing access to mortgage financing in underserved and rural areas.
The USDA 502 loan program faces challenges, including a lack of quality, low-cost housing stock, avoidance of government-backed loans from sellers and realtors, and industry disincentives and lack of flexibility for small-dollar lending. Despite these challenges, Fahe has successfully expanded the visibility, popularity, and uptake of USDA’s 502 loan program. Their hub-and-spoke model, commitment to boots-on-the-ground community engagement, and adaptive program delivery demonstrate a replicable framework for increasing access to mortgage financing in underserved and rural areas.
This case study is adapted from the report Small Loans, Big Barriers: How Small-Dollar Mortgages Impact the Racial Homeownership Gap in the United States and informed by discussions with Fahe leadership and staff in February 2025.
Deputy Director, Future of Land and Housing Program
State Partnerships Lead, Eviction Data Response Network