Gracielle Li
Social Impact Fellow, Teaching, Learning & Tech
This is Part 2 in a two-part series on navigating financial advice on social media.
Click here to read Part 1: Scrolling to Financial Agency: How Gen Z Navigates Financial Advice on Social Media
Social media has changed how young adults encounter financial advice. Posts about credit cards, budgeting, cryptocurrency, investing apps, and debt management now appear alongside entertainment, news, ads, and updates from friends. As a result, financial advice is no longer only something people deliberately seek out; it is also something they encounter while scrolling.
The issue is not that online advice is worse or better than offline advice. Rather, social media changes the context in which financial guidance appears. As discussed in our previous article, advice arrives through algorithmic recommendations, sponsored posts, or influencer endorsements. Content creators (“Finfluencers”) may explain credit, debt, or investing while also benefiting from referral links, sponsorships, paid courses, or platform engagement. This reality can make it harder for users to tell whether a recommendation is meant to explain a financial concept, share a personal experience, entertain viewers, or promote a product.
If social media has become part of the financial information system, responsibility cannot rest solely on individual users to sort good from bad advice. Young adults need tools for evaluating credibility, risk, and incentives, but platforms, regulators, educators, and financial institutions also have a role in making those signals easier to see.
This article uses Jon Roozenbeek and Sander van der Linden’s review of anti-misinformation interventions as a starting point for thinking about financial advice on social media. Roozenbeek and van der Linden, psychologists at the University of Cambridge, study how misinformation spreads and how its influence can be reduced. Their work highlights several strategies relevant here, including 1) correcting false claims after they spread, 2) helping people evaluate information more carefully, and 3) preparing people to recognize manipulation tactics before they encounter them. This article considers how these strategies might apply to financial advice on social media.
Financial misinformation on social media is both a consumer protection and digital literacy problem. Regulators, consumer protection agencies, and platforms already use fact-checking, scam alerts, disclosure rules, and oversight of financial promotions, but these tools work best when users can also recognize how platform design and financial incentives shape the advice they see. Reducing risk requires more than telling young adults to “be careful.” Some interventions correct misinformation after it spreads; others help users recognize risk before acting. This section considers how different approaches work together and where each falls short.
Fact-checking and debunking correct false or misleading claims after they circulate. In financial contexts, this matters because bad information can quickly lead to action: opening an account, buying a product, joining a paid group, or moving money.
These strategies already appear in consumer protection and investor education efforts. The FTC, SEC, FINRA, and state attorneys general regularly issue alerts about investment scams, misleading promotions, social media stock tips, and fraud schemes. These alerts help consumers recognize warning signs such as guaranteed returns, pressure to act quickly, vague documentation, or claims that seem too easy or too certain. Platform tools such as Community Notes on X can also correct misleading posts, though their impact is often dampened by the fact that corrections often appear long after content has already gone viral.
Fact-checking remains limited because much online financial advice is not built around one clearly false claim. It may appear as personal experience, opinion, entertainment, or education while leaving out fees, risks, or conflicts of interest. To strengthen fact-checking, alerts should explain not only what is false but what incentives may be shaping the advice, and platforms could give warnings near high-risk financial content. Fact-checking needs to be contextually tied to the decisions users are being encouraged to make.
Media literacy and critical thinking interventions help people evaluate the credibility, evidence, and intent behind the information they encounter. In financial contexts, these skills overlap with financial education but go further. A young adult watching a video about “the best credit card for beginners,” for example, may need to understand credit utilization and interest rates, but they also need to notice whether the creator is using a referral link, whether the card’s fees are discussed, and whether the advice fits someone who may carry a balance from month to month.
These strategies already appear in financial education programs and consumer education resources from agencies such as the FTC, SEC, FINRA, and the Consumer Financial Protection Bureau. To strengthen them, financial education should include platform literacy, showing how sponsorships, affiliate links, algorithms, and creator monetization shape the advice people see. Users should also learn to ask practical questions: Who benefits if I act on this? What risks are missing? Does this advice apply to my situation?
Media literacy cannot remove every risk from online financial advice, but it can help young adults move from asking “Is this true?” to “What is this content trying to get me to do, and what information should I know before acting on it?”
Prebunking helps people recognize misleading tactics before they encounter them. Instead of correcting false claims after they spread, it teaches users to spot patterns that make misinformation persuasive, such as exaggerated certainty, urgency, selective success stories, lifestyle displays, or claims that complex decisions are simple.
In financial social media, prebunking could teach users to recognize red flags before making decisions. A video promising “guaranteed returns” or a “limited-time opportunity” does not need to be individually fact-checked for viewers to recognize the warning signs. Posts that show profits from a trading app while omitting losses, fees, taxes, or risk work the same way. Tools such as DEPICT identify common tactics used to make misleading information persuasive, and those tactics could be adapted to help users evaluate financial content.
Prebunking should be reinforced over time through school programs, public campaigns, financial wellness tools, or short reminders during moments when financial advice is likely to circulate. It is not a substitute for regulation, but it can help users recognize risky patterns before they become realized financial decisions.
Disclosure requirements make commercial relationships easier to see. As Tisha James discusses, influencers can build trust with audiences while also receiving compensation, sponsorships, affiliate income, free products, or other business opportunities. In financial content, this ambiguity is especially consequential: a creator recommending a credit card, trading app, cryptocurrency platform, or financial course may benefit when followers click, sign up, or buy.
Federal consumer protection and financial industry rules already recognize this problem. The FTC’s Endorsement Guides require disclosure when there is a material connection between an advertiser and an endorser. FINRA guidance emphasizes that financial communications must be fair, balanced, complete, and not misleading.
To strengthen this approach, James argues for stronger enforcement tools, including clearer penalties, shared responsibility between brands and influencers, and audits of sponsorship disclosures. Similar tools could be adapted for financial content, where unclear disclosure may shape whether users borrow, invest, or take on financial risk.
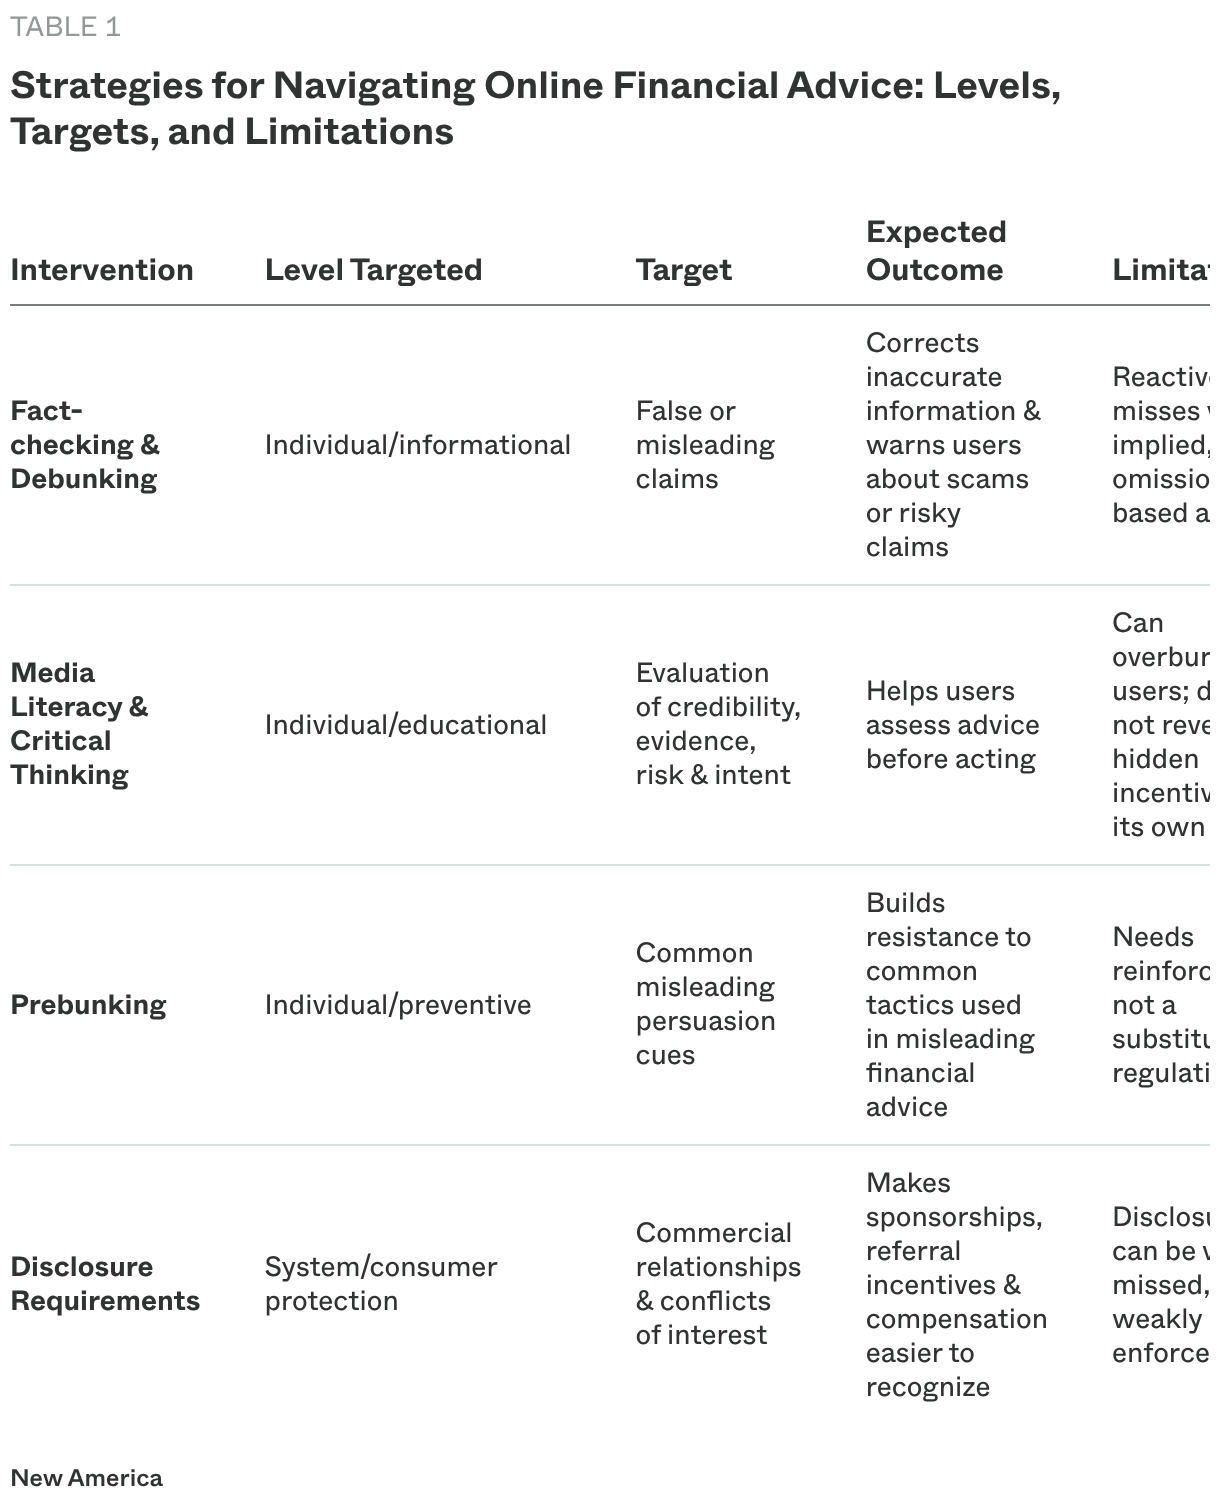
As Table 1 shows, these strategies work at different levels. Fact-checking and debunking correct misleading claims after they circulate. Media literacy and prebunking strengthen individual judgment before users act. Disclosure requirements create systemic protections by making sponsorships, referral incentives, and other commercial relationships easier to see. Together, these approaches connect digital financial literacy with consumer protection.
The strategies above show that no single intervention can address the problem on its own. The recommendations below focus on concrete steps that platforms, regulators, educators, and financial institutions could take to make online financial advice easier to evaluate before users act.
These recommendations would not eliminate misleading financial advice from social media, nor should that be the goal. Young adults will continue to encounter financial guidance in fast-moving, entertainment-driven spaces. The goal is to make that guidance easier to evaluate before advice becomes action, shifting some responsibility from individual users to the platforms, regulators, educators, and financial institutions that shape the online financial advice environment.
Social Impact Fellow, Teaching, Learning & Tech
 Video